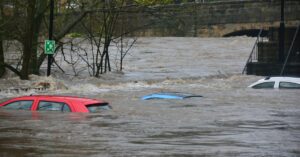
Short answer: A standard homeowners policy usually does not pay for rising floodwater from creeks, rivers, or surface runoff. Flood damage is typically covered only by a separate flood policy, such as one through the National Flood Insurance Program (NFIP) or a private flood insurer. Water entering through a storm-damaged roof or window may be covered under homeowners insurance.
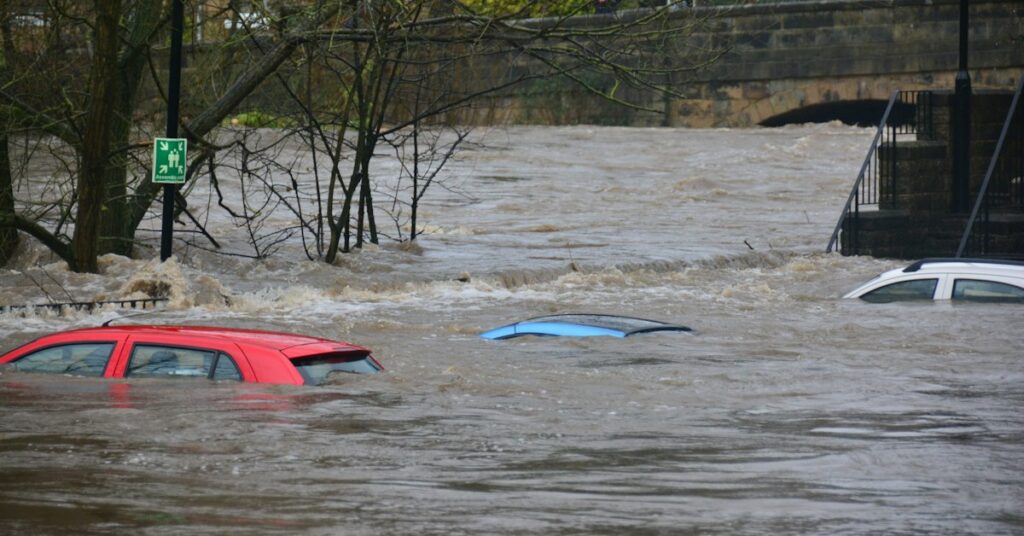
Central Texas is often called “Flash Flood Alley” because thin soils, steep limestone hills, and intense storms can send water rising within minutes. Homes along the Guadalupe near New Braunfels and Seguin, near Cibolo Creek in Boerne, or in low areas near Canyon Lake know how fast it can happen. The insurance question matters as much as the cleanup.
Why doesn’t homeowners insurance cover floodwater?
Homeowners policies typically exclude “flood,” usually defined as surface water, overflow of bodies of water, or rising water, because flood risk is insured separately. That exclusion applies even if your neighborhood has never flooded before.
What’s often treated differently:
- Flood (usually excluded): creek overflow, river rise, surface runoff entering at ground level
- Wind-driven rain (often covered): water entering through a roof, wall, or window damaged by the storm
- Burst pipe (often covered): sudden, accidental water from inside the home
- Sewer backup (often an endorsement): water pushed up through drains
Always read your own policy’s definitions. Wording varies by insurer.
What does NFIP flood insurance actually cover?
NFIP flood insurance has two parts, building coverage for the structure and separate contents coverage for belongings, and each must be purchased. Building coverage generally includes the foundation, electrical and plumbing systems, HVAC, water heaters, built-in appliances, and permanently installed flooring and cabinets.
Points homeowners in the Hill Country often miss:
- Contents coverage is separate and optional
- Coverage in basements and below-grade areas is limited
- There’s usually a 30-day waiting period before a new NFIP policy takes effect
- Private flood policies may offer different limits and options
Check FEMA’s flood maps and FloodSmart.gov to see your zone and coverage details.
How do you know if your damage counts as flood or wind-driven rain?
The deciding factor is how the water entered: rising from the ground is usually flood, while water through storm-damaged openings is usually homeowners coverage. Many storms produce both. A roof damaged by hail and a yard flooded by a creek in the same event can mean two claims under two policies.
Document clues that show the entry point:
- Waterlines on interior and exterior walls
- Roof, window, or siding damage photos
- Debris and silt patterns
- Which rooms were affected first
Dwyer Restoration offers comprehensive inspection and damage consultation, which can help establish what happened and where the water came from.
What does flood damage restoration involve?
Flood damage restoration treats outside floodwater as contaminated, so it includes removal of porous materials, cleaning and sanitizing, structural drying, and rebuilding. Floodwater carries soil, fuel, fertilizer, and sewage, which changes what can be saved.
Typical work includes:
- Mud and water removal
- Removing drywall, insulation, carpet, and pad below the waterline
- Cleaning and sanitizing framing and hard surfaces
- Structural drying with moisture monitoring
- Reconstruction of walls, floors, cabinets, and trim
What drives water damage restoration cost after a flood?
Water damage restoration cost after a flood depends mainly on the height of the waterline, the square footage affected, and how much must be rebuilt. A few inches of water may require a flood cut and new flooring. Several feet can mean replacing lower cabinets, doors, appliances, and HVAC components.
Other cost factors:
- How long water stood in the home
- Contents that must be cleaned, packed out, or discarded
- Code upgrades required during rebuilding
- Access issues if roads or utilities are damaged
Be cautious of anyone quoting a firm price before an inspection.
How do you get water damage insurance claim help after a flood?
Start by reporting to both your flood insurer and homeowners insurer if wind or roof damage is involved, then document everything before cleanup. Clear records speed claims and reduce disputes.
Practical water damage insurance claim help:
- Photograph and video every room, the waterline, and exterior damage
- Keep samples or photos of flooring, drywall, and carpet removed
- List damaged contents with approximate age and value
- Save receipts for emergency repairs and lodging
- Ask your restoration company for moisture logs and a detailed scope
Can you start cleanup before the adjuster arrives?
Yes, you’re generally expected to take reasonable steps to prevent further damage, so start mitigation once it’s safe and document everything first. Waiting days for an adjuster in a humid home in Texas lets damage spread. Photograph thoroughly, keep removed materials or detailed photos, and let your adjuster know mitigation has started.
Related services: Storm Damage Restoration · Comprehensive Inspection & Damage Consultation
Frequently asked questions
Is flood insurance required in San Antonio?
It’s typically required for federally backed mortgages on homes in high-risk flood zones. Homeowners outside those zones can still buy it.
Does flood insurance cover temporary housing?
NFIP policies generally don’t include additional living expenses. Some private flood policies do. Check your policy.
What if my damage is partly flood and partly roof leak?
You may need to file with both insurers. Clear documentation of entry points helps each adjuster assign damage correctly.
Call Dwyer Restoration
If floodwater or storm damage has reached your home in San Antonio or the Hill Country, call Dwyer Restoration at (210) 774-6486 for inspection, cleanup, and rebuilding.